
Poor Cash Flow – Speed Collections and Control Spending
Mystery Business News PR >> Automobile>> Poor Cash Flow – Speed Collections and Control Spending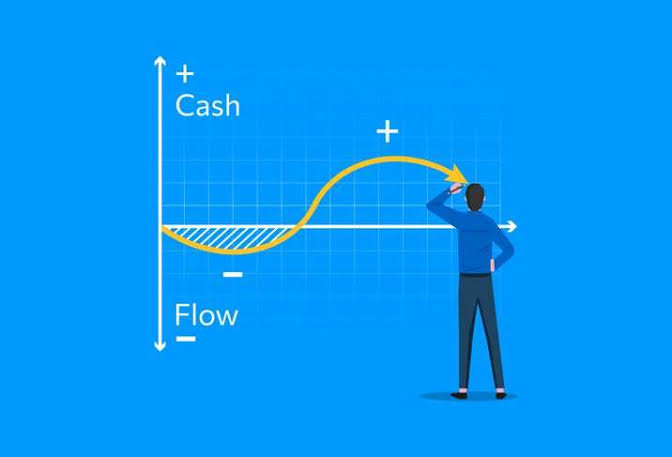
Poor Cash Flow – Speed Collections and Control Spending
Poor cash flow can hurt a business even when sales look healthy on paper. The problem usually appears when money leaves the account faster than customer payments arrive. Improving collection speed, controlling unnecessary spending, and planning upcoming obligations can create breathing room without immediately chasing more revenue.
Find Where Cash Is Getting Stuck
Start by separating profit from available cash. A business may record a profitable month while still struggling to pay suppliers because invoices remain unpaid or large expenses fall due before customer payments arrive.
Create a simple rolling cash forecast covering expected receipts and upcoming bills. The U.S. Small Business Administration offers small-business financial management guidance covering financial controls and recordkeeping that can help owners build better visibility.
Owners often spend time exploring broader business material such as brand visibility ideas, but cash problems deserve attention before discretionary growth projects absorb more money.
Speed Up Customer Collections
Invoice customers immediately after completing work rather than waiting until the end of the week or month. Clearly state payment terms, accepted payment methods, due dates, and contact information so customers have fewer reasons to delay processing.
A consistent reminder process also helps. Send a polite reminder before the due date, another when payment becomes overdue, and follow up personally when a significant balance remains unpaid.
Businesses reviewing promotion planning ideas should also consider whether promotional campaigns create sales that pay quickly or produce receivables that stay outstanding for weeks.
| Cash Flow Problem | Practical Response | Expected Benefit |
|---|---|---|
| Slow invoices | Send bills immediately | Earlier payment cycle |
| Overdue accounts | Use scheduled reminders | Better follow-up |
| Excess purchases | Delay nonessential spending | Preserve available cash |
| Irregular expenses | Forecast upcoming bills | Fewer surprises |
Control Spending Without Damaging Operations
Cutting every expense is rarely the smartest response. Separate costs into essential operations, useful growth spending, and expenses that can be delayed without affecting customers.
Review recurring subscriptions, duplicate software, unused services, excess inventory, and purchases made mainly from habit. Small monthly charges can become meaningful when several accumulate.
The same discipline applies when studying market outreach resources. New outreach may support future revenue, but spending should match current cash capacity rather than optimistic projections.
Build a Cash Buffer Gradually
A reserve gives the business time to respond when customers pay late or unexpected costs appear. Building one does not always require a large transfer. A smaller automatic contribution after strong collection weeks can be easier to maintain.
Consider keeping reserve money separate from the operating account so routine spending does not quietly consume it. The appropriate reserve size depends on payroll, fixed obligations, industry volatility, and how predictable customer payments are.
Where Cash Flow Fixes Often Fail
One common mistake is treating a temporary cash shortage as purely a sales problem. More sales can actually increase pressure when the business must buy materials, hire labor, or extend customer credit before receiving payment.
Aggressive cost cutting can create another problem. Removing maintenance, customer support, or productive staff may protect cash briefly while weakening future revenue. The better approach is to understand timing first, then adjust collections and spending deliberately.
Frequently Asked Questions
Can a profitable business still have poor cash flow?
Yes. Profit records revenue and expenses, while cash flow tracks when money actually enters and leaves the business. Slow-paying customers or large upfront costs can create shortages even during profitable periods.
Should businesses offer discounts for early payment?
Sometimes. A small discount may improve collection speed, but the benefit should be compared with the margin being surrendered. Businesses with thin margins should calculate the cost carefully.
How often should cash flow be reviewed?
Businesses with tight cash positions may benefit from reviewing expected receipts and payments weekly. More stable companies may use monthly forecasting while checking bank balances and major obligations more frequently.
Protect Cash Before Chasing More Growth
Improving cash flow begins with visibility. Know which invoices are outstanding, what bills are approaching, and which expenses can be delayed without harming operations. Once those basics are under control, management can make growth decisions from a stronger position rather than reacting to every short-term shortage.
This article is for general informational purposes and is not a substitute for professional financial advice.
Related Post

Why a List of Property Owners in Dubai is Important
Dubai is a rapidly growing city with a booming real estate market, making it an…